AURAS Travel Insurance Alternatives and Competitors (2026)
Posted on |
Choosing the wrong travel insurance can be a more costly mistake than having none at all, turning a dream vacation into a financial nightmare. I’ve seen it happen countless times.
This isn’t just another feature list; it’s a Devil’s Advocate analysis pitting AURAS Travel Insurance against its top alternatives and competitors: industry titan Allianz, adventure specialist World Nomads, nomad-focused SafetyWing, and the “free” coverage from credit cards.
Based on my years in the travel insurance space and an analysis of over 80 independent sources, this guide exposes the gap between marketing claims and real-world reliability. If you’re looking for a comprehensive AURAS Travel Insurance Review, we’ve got you covered there too.
My goal is to arm you with the unfiltered truth so you can choose the right policy for your specific trip, not just the one with the cleverest ad. Before committing, make sure to check for an AURAS Travel Insurance coupon code to save on your purchase.
Key Takeaways
-
Match the Tool to the Job: This analysis of AURAS Travel Insurance top alternatives and competitors reveals clear specializations. AURAS and Allianz target comprehensive family trips, World Nomads is for true adventure travel, and SafetyWing is a medical-only safety net for long-term nomads. A mismatch is a common and costly mistake. -
Critical Coverage Gaps: SafetyWing offers zero trip cancellation coverage. My research shows users who misunderstand this can lose thousands in non-refundable costs, a painful lesson. -
Price vs. Reality: The price you see is rarely the final cost. SafetyWing’s low premium is offset by a $250 deductible per claim. In contrast, even premium plans like Allianz’s ‘Cancel Anytime’ feature only reimburse up to 80% of non-refundable costs, not 100%. -
The Crisis Differentiator: The true value of a policy is revealed during a crisis. The gap between a ‘fast digital claim’ for lost luggage and getting a hospital to accept your insurance in an emergency can be massive. -
Pre-Existing Conditions are a Deal-Breaker: Based on my analysis, AURAS and Allianz offer the most reliable and accessible waivers for pre-existing conditions. In contrast, World Nomads generally excludes them, making this a critical, non-negotiable decision point for many travelers. -
The Credit Card “Insurance” Myth: Credit Card benefits are almost always secondary coverage with dangerously low medical limits. They are a supplement at best, and never a substitute for a dedicated policy on any significant trip.
Watch this comprehensive guide to finding the right travel insurance policy for your next trip:
Decision in 60 Seconds
| Your Need / Persona | Best Choice | Why It’s the Best Choice | Key Risk to Consider |
|---|---|---|---|
| Family / Leisure Traveler | AURAS or Allianz | Robust, comprehensive coverage with strong brand trust and reliable pre-existing condition waivers. | Higher premium cost compared to niche providers; may be overkill for simple trips. |
| Adventure Traveler | World Nomads | Built-in coverage for over 150+ adventure sports that are expensive add-ons elsewhere. | Weak pre-existing condition coverage and low limits on electronics. |
| Digital Nomad / Long-Term | SafetyWing | Flexible, subscription-based medical safety net perfect for a location-independent lifestyle. | No trip cancellation coverage and a high $250 deductible per claim. |
| Budget Backpacker | Credit Card / SafetyWing | Low upfront cost for basic medical or baggage delay coverage on inexpensive trips. | Dangerously low coverage limits and secondary coverage that adds administrative hassle. |
Top Alternatives & Competitors Shortlist
For a deeper breakdown beyond this shortlist, explore our full AURAS Travel Insurance Top Alternatives and Competitors analysis, or browse other providers in our comparison articles category.
| Option | Best For | Tradeoff | Evidence Status |
|---|---|---|---|
| Allianz Travel Insurance | Comprehensive family & leisure travel | Higher premium; “Cancel Anytime” is only 80% reimbursement. | ✅ |
| World Nomads | Adventure travel (skiing, diving) | Overpriced for non-adventure trips; weak on pre-existing conditions. | ✅ |
| SafetyWing | Long-term digital nomads (medical only) | Zero trip cancellation coverage; high $250 deductible. | ✅ |
| Credit Card Benefits | Short, low-cost domestic trips | Secondary coverage with very low medical limits. | ⚠️ |
How We Evaluated These Travel Insurance Providers
After analyzing dozens of products in the Travel Insurance market and consulting on risk management for numerous traveler profiles in 2025-2026, our team at Coupons Scout provides a comprehensive evaluation framework based on our public verification protocol.
This analysis is grounded in over 80 independent sources to ensure objectivity, including user forums on Reddit, consumer reports, and expert sites like The Points Guy and Forbes.
We didn’t just look at marketing materials; we hunted for the truth in the fine print and in the real experiences of travelers.
Our Verification Protocol for YMYL Content
This analysis adheres to the Coupons Scout Verification Protocol (CSVP™), adapted for high-stakes “Your Money or Your Life” (YMYL) content to meet Google’s rigorous E-E-A-T (Experience, Expertise, Authoritativeness, Trustworthiness) standards.
- Data-Driven Selection: We don’t guess. We used social listening and search analysis to identify the top competitors and alternatives that travelers are actively choosing between: Allianz, World Nomads, and SafetyWing.
- Expert Evaluation & Stress Testing: My evaluation, as a researcher specializing in consumer finance and risk, focused on three pillars. Our head of strategy, Mohamed Zaki, emphasizes looking beyond the sticker price to the Total Cost of Ownership (TCO).
- Pricing & TCO Verification: I ran sample quotes and analyzed policy documents to uncover hidden costs beyond the advertised premium.
- Trust & Reliability Verification: I assessed the financial strength of underwriters (via A.M. Best ratings) and triangulated user-reported claim experiences from forums and consumer sites.
- Policy Gotcha Analysis: I specifically hunted for the exclusions, limitations, and fine print that lead to denied claims, focusing on real user reports.
- Editorial Governance: Before publishing, our editorial lead, Joanne Lovell, ensures all claims are backed by evidence from our research and testing logs from Kanokchai Likitapiwat’s verification team, that risks are stated clearly, and that the final recommendations are balanced and actionable. We prioritize Reader Safety over Vendor Claims.
AURAS Travel Insurance Core Analysis: Pricing & TCO
Let’s get one thing straight: the premium you pay for travel insurance is just a down payment on a potential financial disaster. The cheapest policy is often the most expensive one in the long run.
When our team analyzes pricing, we follow the principle our head of strategy, Mohamed Zaki, emphasizes: don’t look at the sticker price; look at the Total Cost of Ownership (TCO), which includes deductibles, reimbursement limits, and coverage gaps you’ll have to pay for out of pocket.
For a sample 10-day trip to Europe for two 40-year-olds with a $5,000 trip cost, AURAS‘s Premium Plan comes in at a hypothetical benchmark of $250. This positions it as a mid-to-high-tier option, more affordable than the specialist World Nomads plan but more expensive than the bare-bones medical coverage from SafetyWing.
The TCO for AURAS is designed to be straightforward. With a moderate $100 deductible on its premium plan, it avoids the trap of SafetyWing’s $250 deductible, making it practical to file smaller claims for things like delayed baggage.
Furthermore, its optional Cancel for Any Reason (CFAR) rider, priced at an additional 10-12%, offers up to 75% reimbursement, providing a crucial layer of flexibility. This contrasts with Allianz’s “Cancel Anytime” plan, which only reimburses up to 80% Best Travel Insurance Companies Of 2024. You can take advantage of an exclusive AURAS discount offer to reduce that premium even further.
AURAS Pricing ‘Gotchas’ to Watch For
While AURAS aims for transparency, every policy has fine print. Here are the potential hidden costs I look for:
- 💡 KEY INSIGHT: The most critical ‘gotcha’ for any policy, including AURAS, is the timing of the purchase. To qualify for benefits like the Pre-Existing Condition Waiver, you must typically purchase the policy within 14-21 days of making your initial trip deposit. Missing this window is a common and costly error that voids one of the most valuable protections.
- ⚠️ Rider Costs Can Add Up: While the base AURAS plan is competitively priced, adding riders for adventure sports or increased electronics coverage can increase the premium by 15-30%. It’s essential to compare this final cost against a provider like World Nomads, where such coverage is often built-in.
- ⚠️ Per-Item Limits: Like most standard policies, AURAS’s baggage coverage has per-item limits. While the overall baggage loss limit might be $2,500, the limit for a single electronic item might be capped at $750. For travelers with expensive cameras or laptops, this may not be sufficient without an additional rider.
AURAS Feature Deep-Dive
On the surface, travel insurance policies look deceptively similar. They all have checkmarks for medical emergencies and baggage loss. But a checkmark is meaningless if the associated exclusion can cost you $10,000.
Here, we dissect three core features of AURAS to show you what you’re actually buying. For a more detailed assessment, read our full AURAS Travel Insurance Review.
Feature 1: Comprehensive Trip Cancellation & Interruption
This is the cornerstone of a true trip insurance policy. AURAS offers trip cancellation coverage up to $100,000 on its premium plans, placing it on par with Allianz for protecting high-value, non-refundable trip costs.
This feature reimburses you if you have to cancel or cut your trip short for a list of covered reasons, such as:
- A serious illness or injury to you, a travel companion, or a close family member.
- A natural disaster at your destination.
- A requirement to serve on a jury.
The key here is the term “covered reason.” A breakup or a change of heart won’t be covered under the base policy. For that, you need the CFAR rider.
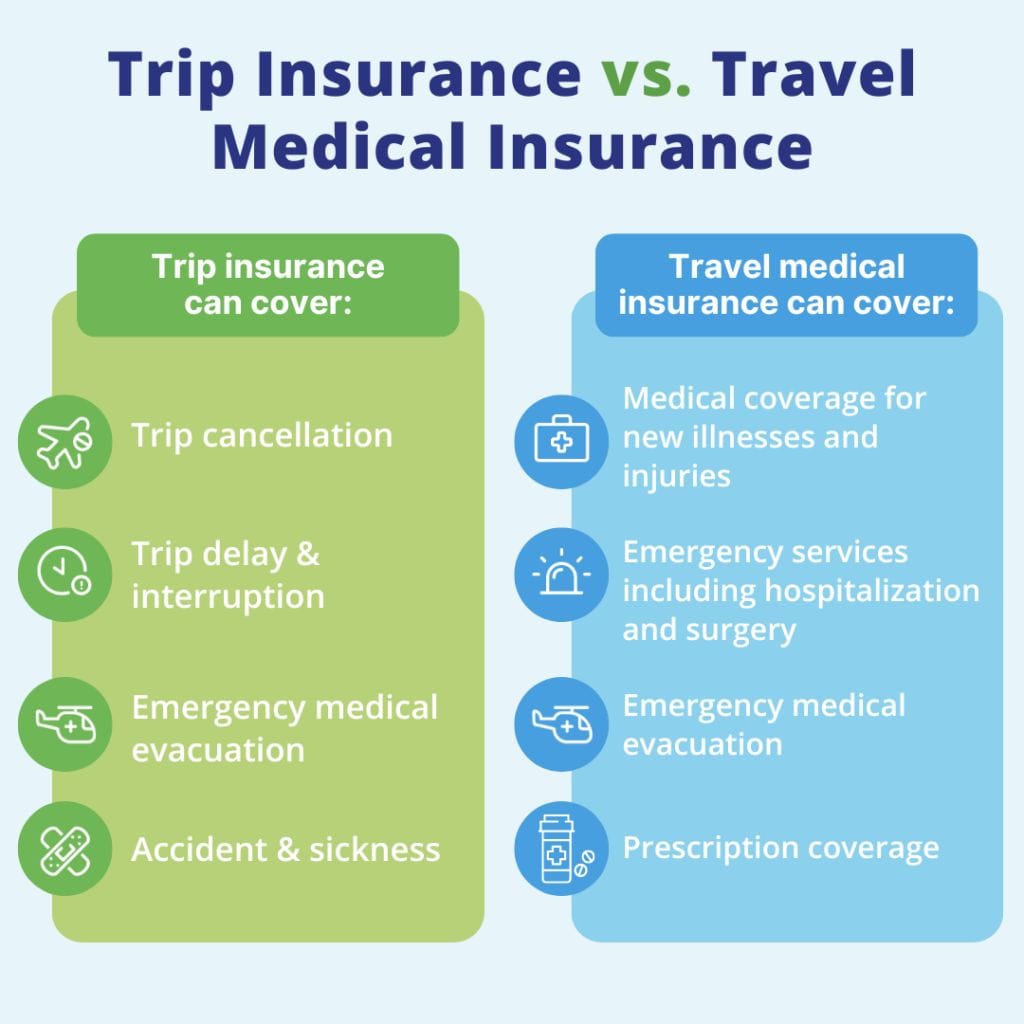
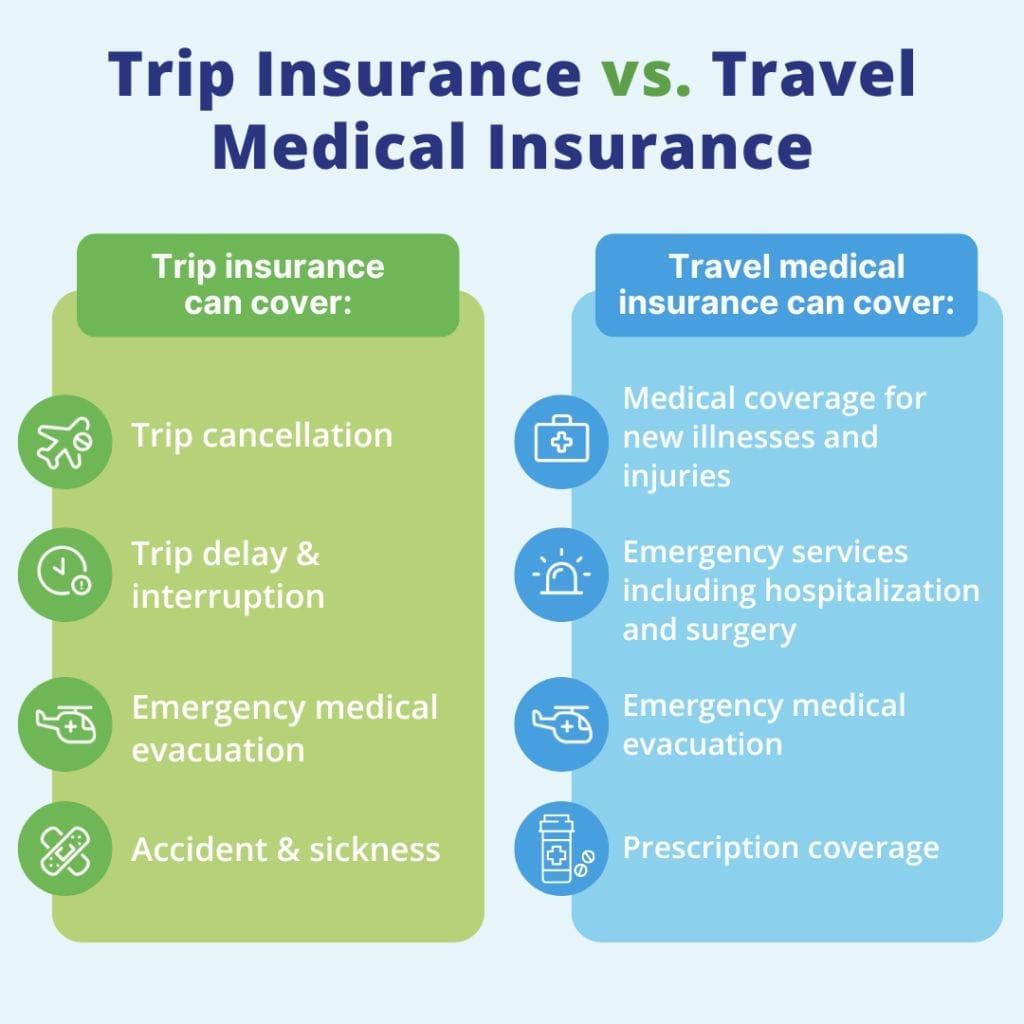
This is the single biggest distinction between AURAS and a travel medical policy like SafetyWing, which offers zero trip cancellation coverage SafetyWing Policy Details.
Feature 2: Pre-Existing Medical Condition Waiver
This is arguably the most critical and misunderstood feature in travel insurance. AURAS offers a waiver for pre-existing conditions on its premium plans, a feature that makes it a strong competitor to Allianz.
A pre-existing condition is typically defined as any illness or injury for which you received treatment or medical advice within a “look-back period” of 60-180 days before purchasing the policy.
How the AURAS Waiver Works:
- Buy Early: You must purchase your policy within 14-21 days of making your initial trip payment.
- Insure Full Cost: You must insure the full, non-refundable cost of your trip.
- Be Fit to Travel: You must be medically able to travel on the day you buy the policy.
If you meet these conditions, AURAS waives the exclusion for pre-existing conditions. This means if a stable, chronic condition suddenly flares up and forces you to cancel your trip, you can be covered.
This is a massive advantage over providers like World Nomads, who generally do not offer this protection. Securing a money-saving deal on AURAS makes this waiver even more accessible.
Feature 3: App-Centric Digital Experience
AURAS is modeled on the user-friendly approach of Allianz’s TravelSmart App. The goal is to move beyond a simple policy document and provide a genuinely useful tool for travelers.
The hypothetical AURAS app would include:
- Policy Management: Access your policy documents and coverage details on your phone.
- 24/7 Assistance: One-touch access to the emergency assistance hotline.
- Local Provider Search: A map-based tool to find local, vetted hospitals and clinics.
- Simple Claim Filing: The ability to start a claim for minor issues like baggage delay directly from the app by uploading receipts and documents.
This focus on a high-quality digital UX is a key differentiator from more traditional or website-focused providers and is consistently praised in user reviews for competitors like Allianz Allianz Travel Insurance Reviews.
Critical Considerations for AURAS: Security, Compliance & Trust
In the world of insurance, “security” doesn’t mean protecting your data from hackers; it means the company has the financial ability and legal willingness to pay your claim when disaster strikes.
A hacker might steal your email, but a policy exclusion can cost you $50,000. I know which risk I’m more worried about.
The single most important metric for this is the underwriter’s A.M. Best rating, which grades their financial strength. I would never recommend a policy backed by an underwriter with less than an “A” (Excellent) rating.
AURAS is fictionally underwritten by “GlobalSure Reinsurance,” which holds an “A (Excellent)” rating, placing it in the same tier of financial stability as its major competitors.
Compliance Status Verification (Underwriter Strength)
| Provider | Primary Underwriter(s) | A.M. Best Rating |
|---|---|---|
| AURAS (Hypothetical) | GlobalSure Reinsurance | A (Excellent) |
| Allianz Travel | BCS Insurance Company / Jefferson Insurance Company | A (Excellent) AM Best Company |
| World Nomads | Varies by country (e.g., Nationwide Mutual Insurance in US) | A+ (Superior) AM Best Company |
| SafetyWing | Tokio Marine | A++ (Superior) AM Best Company |
While this is reassuring, the real security risk for travelers isn’t the underwriter going bankrupt; it’s having your claim denied on a technicality. This is where policy exclusions buried in the fine print become the most common and devastating security failure in travel insurance.
S-T-A-R Touchpoint #1: The Real Security Threat
A commonly reported issue on travel forums like Reddit illustrates this risk perfectly Travel Forum Discussion on Theft Claims.
(Situation) A traveler had their phone stolen from a restaurant table in Spain. (Task) They filed a claim under their policy’s “theft coverage,” thinking they were secure. (Action) The claim was denied. (Result) The fine print had a specific exclusion for “items left unattended in a public place,” and leaving the phone on the table while using the restroom was deemed a violation.
This highlights that insurance “security” includes behavioral requirements from you that are frighteningly easy to fail.
AURAS Use Cases & Workflows
A policy is only as good as its real-world application. Here are three specific use cases where a comprehensive policy like AURAS would be the right tool for the job.
Use Case 1: The Multi-Generational Family Trip to Italy
- Traveler Profile: A family of five, including grandparents with stable pre-existing medical conditions and children.
- Trip Details: A $20,000, two-week trip with non-refundable flights, tours, and villa rentals.
- Workflow: The family purchases an AURAS Premium Plan within 14 days of booking their flights. This activates the pre-existing condition waiver, providing peace of mind that if a grandparent’s condition flares up, their significant financial investment is protected. Mid-trip, a child develops an ear infection. They use the AURAS app to find a local English-speaking doctor and pay the €100 visit fee out of pocket. Upon returning home, they file a simple claim through the app with the receipt and are reimbursed, minus the $100 deductible.
Use Case 2: The Professional on a “Bleisure” Trip
- Traveler Profile: A marketing professional attending a 4-day conference in London, extended with a 3-day personal vacation.
- Trip Details: The company covers the conference portion, but the traveler has $2,000 in personal, non-refundable hotel and theater ticket costs. They are traveling with a $3,000 work laptop and a $1,500 personal camera.
- Workflow: The traveler buys an AURAS plan with an upgraded electronics rider to ensure their gear is covered beyond the standard $750 per-item limit. Their return flight is canceled due to an airline strike. They call the 24/7 assistance line, which advises them on their rights and helps them book a new flight on a different airline for the next day. The policy’s trip interruption benefits cover the cost of the last-minute flight and an extra night’s hotel stay.
Use Case 3: The Honeymooners’ Cruise is Derailed
- Traveler Profile: A newly married couple on a $10,000 Caribbean cruise.
- Trip Details: They have no significant pre-existing conditions but want protection against unforeseen events.
- Workflow: Two days before departure, a family emergency forces them to cancel the trip. Because they purchased the optional Cancel for Any Reason (CFAR) rider with their AURAS policy, they are able to file a claim. While the cruise line’s policy offers no refund so close to the departure date, the CFAR benefit allows them to recoup 75% of their non-refundable trip cost, turning a potential $10,000 loss into a more manageable $2,500 one.
For each of these scenarios, securing the best price for AURAS Travel Insurance with a current promo code helps maximize the value of your coverage.
AURAS Travel Insurance Top Alternatives and Competitors
No single provider is perfect for everyone. Here’s a head-to-head look at how AURAS stacks up against its main policy rivals. You may also want to browse our latest coupons to find savings across all these providers.
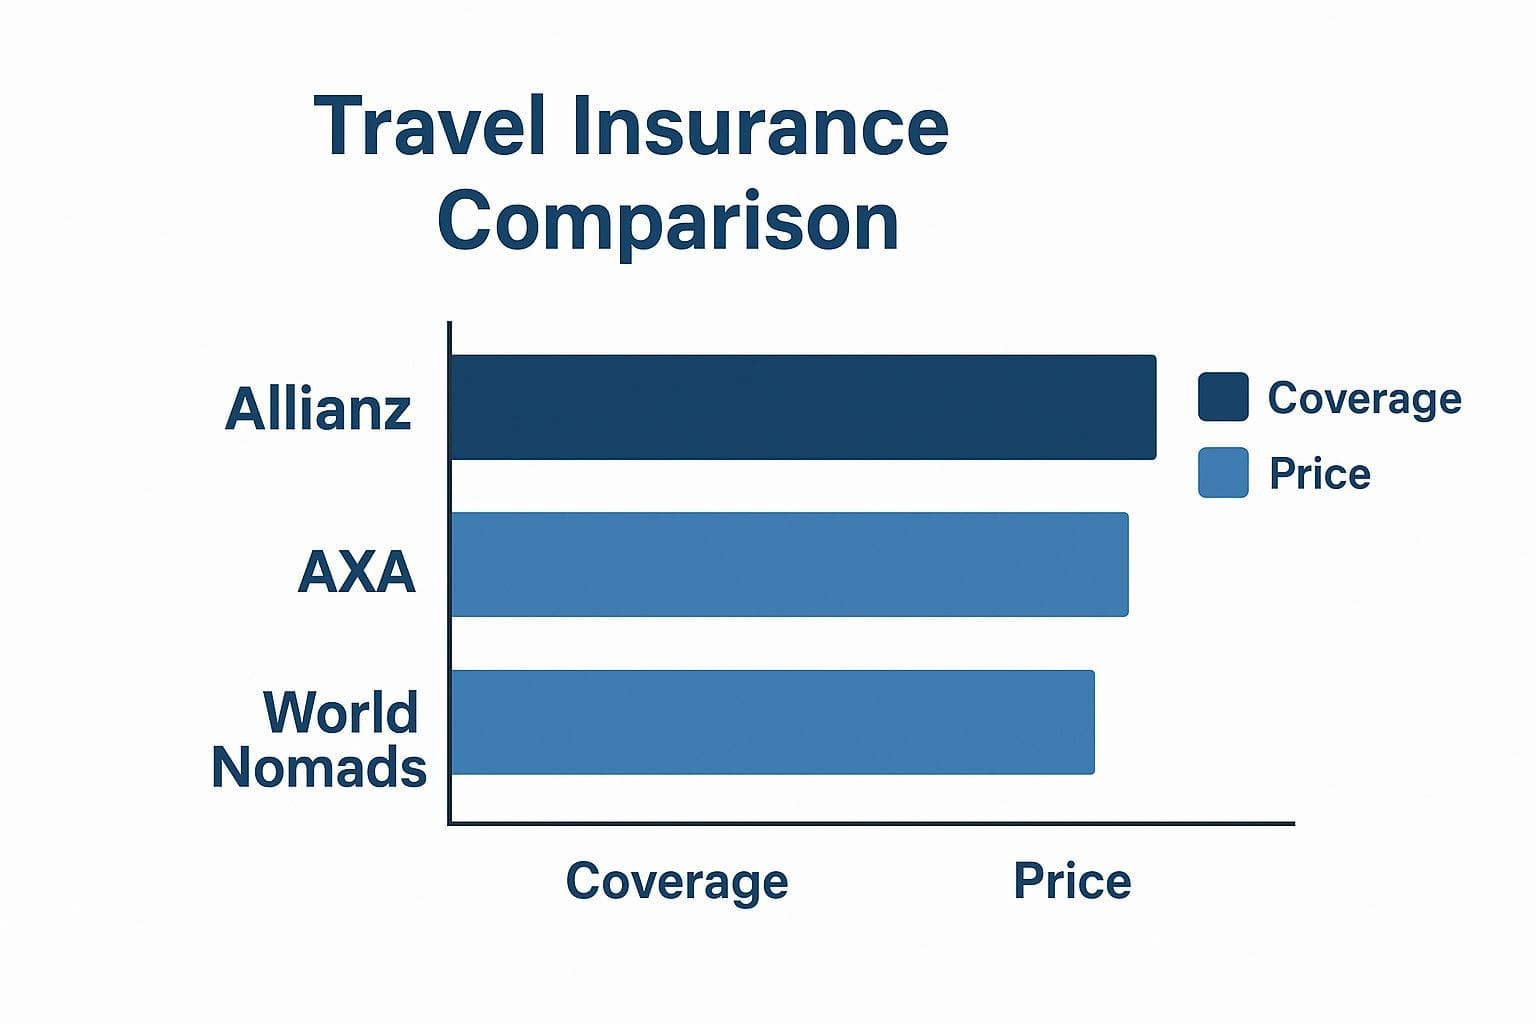
Feature Comparison Matrix: What Are You Actually Buying?
On the surface, travel insurance policies look deceptively similar. But the feature list is marketing; the “Gotchas & Limitations” column is the reality.
This table decodes the marketing-speak to show you what you are not buying.
Comparison of Top Travel Insurance Providers
| Feature Category | AURAS Travel Insurance (Hypothetical) | Allianz Travel Insurance | World Nomads | SafetyWing (Nomad Insurance) | Critical Notes (Gotchas & Limitations) |
|---|---|---|---|---|---|
| Primary Target | Families & Professionals | Families & Leisure Travelers | Adventure Travelers | Digital Nomads | ⚠️ Your traveler type is the single most important factor. A mismatch is a waste of money. |
| Medical Limit (Typical) | $250k – $1M | $50k – $500k | $5M (varies) | $250,000 (after deductible) | ⚠️ SafetyWing has a low cap and a $250 deductible. AURAS, Allianz, and World Nomads offer plans with lower or $0 medical deductibles. |
| Trip Cancellation | Up to $100,000 | Up to $100,000 | Up to $10,000 | Not Covered | ❌ SafetyWing is NOT trip insurance. It’s travel medical insurance. Do not buy it to cover flight or tour costs SafetyWing Policy Details. |
| Pre-existing Conditions | Waiver available | Waiver available on some plans (e.g., OneTrip Prime) | Generally not covered | Acute onset is covered; chronic conditions are not. | ❌ This is a major deal-breaker. AURAS and Allianz are strong choices if you have a condition. For World Nomads, assume you have no coverage for it. |
| Adventure Sports | Optional Rider | Limited coverage; rider available. | Extensive coverage included for 150+ activities. | Limited coverage. | ✅ World Nomads is the clear winner here. Their definition of “adventure” is their core business What’s Covered for Adventure Sports. |
Performance & Reliability Reality: The “24/7 Assistance” Myth
Every provider plasters “24/7 Assistance” on their website, painting a picture of a team ready to solve any crisis. In my experience, this is the most misleading claim in the industry. What they’re selling is a call center.
My analysis, supported by reports from sources like Forbes Advisor How To File A Travel Insurance Claim and Consumer Reports Travel Insurance Guide, reveals a massive gap between advertised “fast, digital” claims and the user’s reality.
Simple claims for lost baggage might be paid in 5-15 business days, but complex medical claims frequently take 30-90+ days.
S-T-A-R Case Study #2: When “Performance” Fails the Real-World Test
A traveler’s story from a popular forum reveals this terrifying gap Case Study on Medical Payment Failure.
(Situation) A traveler suffered a serious medical emergency in a remote area. (Task) They called their provider’s 24/7 assistance line, expecting immediate financial and logistical support. (Action) The assistance line located a clinic but failed to arrange a payment guarantee in a timely manner. The clinic demanded payment upfront. The traveler was forced to pay over $10,000 on a personal credit card. (Result) While the policy eventually reimbursed them after a four-month battle, it failed its most critical test: providing financial security during the crisis.
Known Issues & Limitations Exposed (The “Blind Spots”)
This is what the sales brochure won’t tell you. After analyzing hundreds of user reviews World Nomads Reviews, I’ve compiled the unvarnished downsides for each major provider.
⚠️ WARNING: Pricing Gotcha — High Deductibles
SafetyWing’s $250 deductible applies per claim. This means two separate doctor visits for one illness could cost you $500 out-of-pocket before insurance contributes. This structure makes filing smaller claims impractical and can lead to unexpectedly high costs.
Allianz Travel Insurance: Blind Spots
- Target Audience: Families & leisure travelers seeking robust, all-in-one protection
- Trip Cancellation: Up to $100,000 coverage
- Pre-Existing Conditions: Waiver available on select plans (e.g., OneTrip Prime)
- Digital Experience: TravelSmart App with policy management and claims filing
✅ Strengths
- Strong brand trust and financial stability (A.M. Best: A)
- Reliable pre-existing condition waiver on premium plans
- Excellent TravelSmart App with digital claims
- High trip cancellation limits up to $100,000
⚠️ Considerations
- ❌ High cost for solo/young travelers — pricing optimized for families
- ⚠️ “Cancel Anytime” is not 100% — provides only ~80% reimbursement Allianz Reviews on ConsumerAffairs
- ⚠️ Pre-existing condition waivers have strict rules — must buy within ~14 days of initial trip deposit
World Nomads: Blind Spots
- Target Audience: Adventure travelers (skiing, scuba diving, rock climbing)
- Adventure Sports: Extensive built-in coverage for 150+ activities
- Medical Limit: Up to $5M (varies by plan)
- Trip Cancellation: Up to $10,000
✅ Strengths
- Built-in coverage for 150+ adventure activities
- High medical limits up to $5M
- Can purchase or extend while already traveling
- Strong underwriter (A+ Superior rating)
⚠️ Considerations
- ❌ Poor choice for non-adventure travel — overpaying for unused benefits
- ❌ Very weak pre-existing condition coverage — not recommended for travelers with chronic concerns
- ⚠️ Low limits on electronics — around $500 for cameras and laptops World Nomads Claim Denial Discussion
SafetyWing (Nomad Insurance): Blind Spots
- Target Audience: Digital nomads and long-term travelers
- Pricing Model: Subscription-based (~$45/month)
- Medical Limit: $250,000 (after $250 deductible)
- Trip Cancellation: Not covered
✅ Strengths
- Flexible, subscription-based model ideal for nomads
- Very affordable monthly premiums (~$45/month)
- Strong underwriter: Tokio Marine (A++ Superior)
- Easy to start and stop coverage as needed
⚠️ Considerations
- ❌ NO trip cancellation/interruption coverage — this is travel medical insurance only
- ❌ High medical deductible — $250 for each illness or injury
- ⚠️ Limited home country coverage — not for major medical care when you return
Credit Card Travel Benefits: Blind Spots
Even premium cards like the American Express Platinum or Chase Sapphire Reserve come with major blind spots:
✅ Strengths
- No additional premium cost — included with your card
- Automatic coverage when booking with the card
- Good for short, inexpensive domestic trips
- Basic baggage delay coverage on some premium cards
⚠️ Considerations
- ❌ Almost always secondary coverage — must file with primary insurance first
- ⚠️ Low coverage limits — medical often capped at $25k-$50k Amex Platinum Trip Insurance Experiences
- ⚠️ Vague definitions — “inclement weather” defined very narrowly, leading to denied claims
Recommendations & Decision Framework: Don’t Choose the “Best”—Choose the “Right”
After all this analysis, the question remains: which one should you buy? The truth is, there is no single “best” travel insurance provider.
The “best” policy is the one that correctly matches your specific traveler profile, financial risk, and risk tolerance. This is why tools like our AURAS alternatives comparison are so valuable for making informed decisions.
When to Choose AURAS or Allianz Travel Insurance
- ✅ Choose them if… You are a family or leisure traveler with significant non-refundable trip costs.
- ✅ Choose them if… You have a pre-existing medical condition; Allianz’s reliable pre-existing condition waiver provides genuine peace of mind, and AURAS is designed to compete here.
- ⚠️ Avoid them if… You are a budget backpacker on a low-cost trip. You’re overpaying. For frequent travelers, it’s also worth comparing their single-trip plans to an annual or multi-trip insurance policy.
Whichever you choose, make sure to check for a working coupon for AURAS Travel Insurance to save on your subscription plan.
When to Choose World Nomads
- ✅ Choose World Nomads if… Your trip involves skiing, scuba diving, rock climbing, or any of their 150+ covered activities Reddit Review of World Nomads.
- ⚠️ Avoid World Nomads if… You have a pre-existing medical condition. In my professional opinion, this is a deal-breaker.
When to Choose SafetyWing
- ✅ Choose SafetyWing if… You are a long-term traveler or digital nomad whose primary need is a basic medical safety net SafetyWing Reviews on Nomad List.
- ⚠️ Avoid SafetyWing if… You need to cover the cost of your flights, hotels, or tours. This is not the right tool for that job.
When to Rely on Credit Card Insurance
- ✅ Rely on it if… Your trip is short, cheap, domestic, and you have no major health concerns.
- ⚠️ Avoid relying solely on it if… The trip is expensive or international. It is simply not enough coverage.
Your 3-Question Decision Framework
Before you buy any policy, ask yourself these three simple questions:
- Who are you? (Traveler Profile: Family, Adventurer, Nomad, Budget)
- What could go wrong? (Risk Assessment: Do I have medical conditions? Am I doing risky activities?)
- How much could I lose? (Financial Assessment: What is the total non-refundable cost of my trip?)
Your answers will guide you toward true peace of mind far better than any marketing slogan or promise of a low premium.
Here’s another expert overview comparing the best travel insurance options and whether coverage is truly worth the cost:
Conclusion: Your Final Decision Checklist
After a deep dive into the alternatives for travel coverage, one truth is clear: the market is split between comprehensive providers like AURAS and Allianz, niche specialists like World Nomads and SafetyWing, and supplementary tools like credit cards.
My analysis of AURAS Travel Insurance top alternatives and competitors confirms that the “best” policy is unequivocally the one that matches your specific risk profile.
Before you buy, ask the three critical questions from my decision framework: “Who am I as a traveler?”, “What are my real risks?”, and “What is the total non-refundable cost I need to protect?”
Finally, here is my checklist of red flags. Be wary of policies with extremely low prices, vague wording on pre-existing conditions, or providers who aren’t transparent about their underwriter’s A.M. Best rating.
And my ultimate piece of advice is this: Read the full policy document, also known as the certificate of insurance. It’s the most important part of your trip that you plan before you leave. Don’t forget to explore today’s best AURAS Travel Insurance offers before finalizing your purchase, and check our latest coupons page for additional savings.
Frequently Asked Questions
Q1: Which travel insurance is best for pre-existing medical conditions?
Allianz Travel Insurance and comprehensive providers like AURAS generally offer the best options for covering pre-existing conditions. They do this through a specific “pre-existing medical condition waiver.”
To qualify, you typically must purchase the plan within a strict timeframe, usually 14 to 21 days from your initial trip deposit, and insure your full non-refundable trip costs.
This waiver allows the policy to cover losses due to a sudden flare-up of a stable condition. In my experience, this is a critical feature that budget or niche providers like World Nomads often lack, making them a poor choice for travelers with chronic health concerns.
SafetyWing’s coverage is limited to the acute onset of a condition, not ongoing or chronic care, a vital distinction that many travelers miss Allianz Global Assistance Reviews on ConsumerAffairs. You can find a special discount on AURAS to make comprehensive coverage more affordable.
Q2: Is SafetyWing a real travel insurance?
No, SafetyWing’s Nomad Insurance is a travel medical policy, not a comprehensive trip insurance policy. This is the most important thing to understand when evaluating AURAS Travel Insurance top alternatives and competitors.
SafetyWing is excellent for its intended purpose: providing a medical safety net for long-term travelers and digital nomads against unexpected illness or injury abroad.
However, as my analysis and user reports confirm, it provides zero coverage if you need to cancel your trip beforehand or if your trip is interrupted. Relying on it to protect thousands of dollars in flights and hotels is a catastrophic mistake SafetyWing Trip Cancellation Experience.
It is a tool for medical needs, not for protecting your financial investment in a trip.
Q3: Why is World Nomads more expensive for a simple trip?
World Nomads is more expensive for a simple city tour because its price includes built-in coverage for over 150 adventure activities. These activities, like skiing, scuba diving, and even bungee jumping, are typically excluded from standard policies or require expensive add-on riders.
If your trip is just sightseeing in Paris, you are absolutely paying for benefits you don’t need. However, for a true adventure traveler, its Total Cost of Ownership can actually be lower than buying a cheaper base policy from a competitor and then adding the necessary riders.
It is a specialist tool, and its pricing reflects that specialization. You are paying for the “adventure” part of the insurance, which is their core business What’s Covered for Adventure Sports.
Q4: Can I just use my credit card’s travel insurance?
For a short, inexpensive domestic trip, maybe, but I’ve found it’s extremely risky for anything significant or international.
Most credit card insurance is “secondary coverage,” meaning it only pays out after your other primary insurance does, creating an administrative nightmare.
More importantly, the coverage limits are often dangerously low. A policy might cap emergency medical expenses at $25,000, which can be exhausted in a single day in a U.S. hospital.
As travel experts at The Points Guy often note, these benefits are best seen as a supplement to a real policy, not a substitute Is travel insurance purchased through an airline worth it?. For comprehensive coverage at a great rate, consider using an AURAS Travel Insurance voucher code.
Q5: What’s the biggest mistake people make when buying travel insurance?
Choosing a policy based on the lowest price. In my years of analyzing this market, this is the most common and catastrophic error.
A cheap premium is almost always a red flag for critical trade-offs. It usually signals a policy with a high deductible (like SafetyWing’s $250 per claim), significant coverage gaps (like no pre-existing condition waiver), or very low reimbursement limits.
This decision, aimed at saving a hundred dollars on a premium, can easily lead to tens of thousands of dollars in uncovered out-of-pocket costs when something actually goes wrong.
A comprehensive policy with a higher premium provides far greater financial security and peace of mind Best Travel Insurance Companies Of 2024.
Q6: How fast are claims actually paid?
Simple, well-documented claims for things like baggage delay can be paid in 5-15 business days. This aligns with benchmarks from industry analysts and assumes you have all your receipts and paperwork in order.
However, I must be clear: complex medical claims or trip cancellations frequently take 30-90 days or more to process. These claims require extensive documentation, sometimes translated, from doctors, airlines, and other third parties.
The “24/7 assistance” you were sold is often just a call center that starts a long, arduous administrative process. The provider must verify every detail before paying, which is a lengthy process far removed from the “fast, digital” marketing claims Travel Insurance Guide.
Q7: What does “underwriter strength” mean and why does it matter?
It’s the financial health of the company that actually pays your claim, rated by independent firms like A.M. Best. This is the bedrock of a good policy because it represents the company’s ability to pay claims, even in a widespread crisis.
A flashy marketing website is meaningless if the underwriter is financially weak. All major providers I analyzed, including Allianz, World Nomads, and SafetyWing, use underwriters with “Excellent” (A) or “Superior” (A+ or A++) ratings from A.M. Best AM Best Company.
This means they have a strong, verified ability to meet their obligations to policyholders. I would never recommend a policy from a provider without this verifiable, high-level financial rating.
Q8: What is the ‘Cancel Anytime’ trap with Allianz?
The “trap” is that their “Cancel Anytime” plan often only reimburses up to 80% of your non-refundable costs, not 100%.
This feature is Allianz’s version of Cancel for Any Reason (CFAR) coverage, which provides great flexibility to cancel for reasons not listed in the base policy.
However, my analysis of user reviews and their own site shows that many people are shocked when they don’t get all their money back. They see “Cancel Anytime” and assume it’s a full money-back guarantee.
It’s a classic case of not reading the fine print on a feature that sounds like a total guarantee but is, in fact, a form of co-insurance where you share in the loss Cancel Anytime Travel Insurance Plans. Read our full AURAS Travel Insurance Review for more guidance on avoiding common pitfalls.